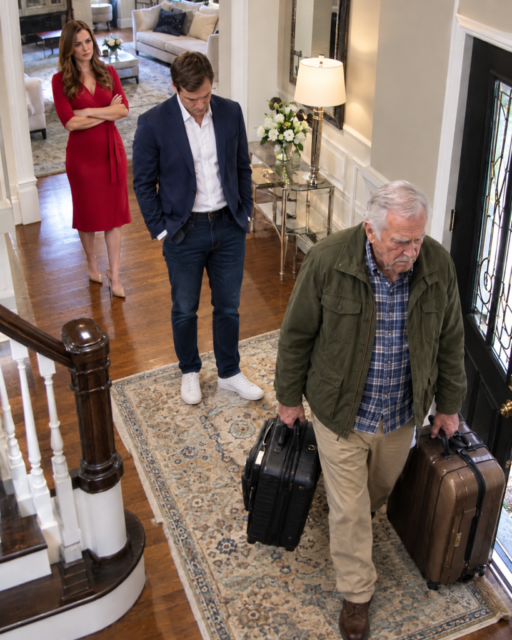

My daughter-in-law told me to disappear into my bedroom while her guests were still sitting at the dinner table. Then she turned toward my son and said, “Logan, are you going to do something about your father?” I waited for him to defend me, but he stared into his glass and whispered, “Dad, maybe you should give us some space.” That night, I decided to leave. Neither of them knew that I had nearly $800,000 in investments—or how much of their comfortable life depended on my financial support.
My name is Albert Higgins. I’m sixty-eight years old, a retired senior accountant, and a widower.
Six years earlier, when my wife Margaret passed away, Logan invited me to live with him and his wife, Chelsea, in Dallas, Texas.
At first, I was grateful.
After forty years of marriage, returning to an empty house felt unbearable. I missed Margaret’s laughter, her morning coffee, and the way she always left the porch light on when I worked late.
Logan assured me I would always have a place with his family.
For a while, I believed him.
I helped with groceries, cooked dinner several nights a week, and occasionally picked up supplies for Logan’s renovation business.
Then Chelsea began making little comments.
“Albert, would you mind eating in the kitchen tonight? We’re having friends over.”
A few months later, she asked me to stay upstairs whenever her coworkers visited.
Eventually, she suggested I use the back entrance so guests wouldn’t see me walking through the living room.
Each request seemed small enough to ignore.
Together, they made me feel like an unwanted stranger.
What Chelsea didn’t know was that I had spent decades saving and investing carefully. My retirement income covered my needs, and my investment portfolio had grown to approximately $800,000.
I wore old sweaters because they were comfortable, not because I couldn’t afford new ones.
More importantly, I had quietly helped Logan and Chelsea build the lifestyle they enjoyed.
When Logan’s renovation company needed additional financing, I pledged part of my investment portfolio as collateral for a business credit line.
When their house required major repairs, I provided a documented family loan of $186,400.
I also established an account to help with household expenses.
I never demanded praise.
I only hoped my son understood that I was helping because I loved him.
That Monday evening, Logan invited several coworkers to dinner.
I spent the afternoon preparing stuffed mushrooms, his favorite childhood appetizer. Margaret used to make them whenever he brought home a good report card.
When I carried the tray into the dining room, Chelsea barely glanced at it.
“Albert, please stop hovering.”
I stepped aside.
A few minutes later, she approached again.
“Why don’t you stay in your room tonight?”
I looked at her.
“I was just bringing out the food.”
“We have company. I don’t want everyone feeling uncomfortable.”
Several guests had heard her.
Then she turned toward Logan.
“Are you going to handle this?”
The room became painfully quiet.
I looked at my son.
He stared at his drink.
“Dad,” he finally murmured, “maybe you could give us some space.”
I set the serving tray down.
“Of course.”
Nobody stopped me as I walked upstairs.
Before sunrise, I packed two suitcases containing my clothes, documents, photographs, and laptop.
I left my house key on the kitchen counter.
There was no note.
No argument.
I simply walked away.
The following morning, I met with a contract attorney named Fiona Cartwright.
She examined the financial agreements I’d signed over the previous six years.
“What would you like to accomplish, Mr. Higgins?”
“I want to separate my finances from my son’s household and business.”
She reviewed the documents carefully.
“We can begin that process, but everything must follow the contractual requirements.”
“That’s exactly what I want.”
Over the next three weeks, Fiona coordinated the necessary notices with the bank and investment custodian.
I wasn’t taking money that belonged to Logan or Chelsea.
I was ending financial arrangements I’d never intended to maintain forever.
At precisely 8:30 one morning, three envelopes were delivered to their house.
The first concerned the collateral securing Logan’s business credit line.
The second concerned repayment of the family renovation loan.
The third terminated their access to the household investment account.
I was sitting in Fiona’s office when my phone began ringing.
Logan.
Then Chelsea.
Then Logan again.
I let the calls go unanswered.
For six years, they’d treated me like a burden while depending on financial support they barely acknowledged.
Now they were about to discover what that support had actually meant.
Fiona placed one final document in front of me.
“Albert, there’s something else we need to discuss.”
I looked at the page.
It was a four-year-old investment statement.
At the bottom appeared a figure Logan had never bothered to examine.
$803,417.29.
And beside the account balance were two words that would change everything.
Sole owner.
My son called seven times after receiving the three envelopes. His wife called twice, and an unfamiliar number appeared between their attempts.
I watched my phone light up on Fiona Cartwright’s conference table.
“You’re allowed to answer,” my attorney said.
“I know.”
“You’re also allowed to wait.”
I turned the phone facedown.
For six years, I’d been available whenever Logan needed money, advice, or someone to solve a problem. Yet when I needed him to defend my dignity, he’d looked into his drink.
Fiona reviewed the documents we’d delivered.
The first notice confirmed that my investment securities would no longer secure Logan’s business credit line. His bank had given him thirty days to arrange replacement collateral or refinancing.
The second demanded repayment of the $186,400 renovation loan under our written agreement.
The third ended Logan and Chelsea’s authorization to use the account I’d established for household expenses.
“Everything has been reviewed for compliance with the agreements,” Fiona assured me. “You’re not taking their property. You’re ending financial support that belongs to you.”
I nodded, although the situation still hurt.
“I never wanted to make my son afraid of losing everything.”
“Then why are you doing this?”
“Because I finally realized I was afraid of losing him if I stopped paying.”
Fiona’s expression softened.
“Those are two different problems, Albert.”
That evening, I returned to my rented apartment in Irving. It had a small kitchen, two chairs, and a bedroom with bare white walls.
There were no family photographs yet, but nobody had asked me to hide in it.
The next morning, Logan called again.
This time, I answered.
“Dad? Thank God. Where are you?”
“I’m safe.”
“Why did you disappear?”
I looked toward the window.
“You heard Chelsea tell me to leave the dining room.”
“That wasn’t the same as asking you to move out.”
“No. But it made something clear.”
He sighed.
“Can we please talk about these notices?”
“Of course.”
“The bank says your investments were securing my business loan.”
“That’s correct.”
“I didn’t realize you could withdraw them.”
“You signed the agreement, Logan.”
“I signed a hundred papers that day.”
“And I explained what mine meant.”
Silence followed.
Then he asked about the renovation loan.
“You said you wanted to help us.”
“I did. That’s why I lent you the money.”
“But we’re family.”
“Being family doesn’t turn a signed loan into a gift.”
His voice tightened.
“Chelsea thinks you’re punishing us.”
“I’m protecting my retirement.”
“By putting my company at risk?”
“Your company was already relying on assets it didn’t own.”
I heard Chelsea speaking in the background, asking him to hand her the phone.
“I’m not ready to speak with her,” I said.
“Dad, she wants to explain.”
“Then she can wait.”
Logan sounded stunned.
I’d rarely refused either of them anything.
Finally, I suggested meeting alone at a café the following afternoon.
He agreed.
When he arrived, his shirt was wrinkled, and he looked as though he hadn’t slept.
“I was worried about you,” he said.
“I believe you.”
“Then why didn’t you call?”
“Because I needed to know whether you missed your father or the financial arrangements.”
He looked down.
“That’s unfair.”
“Maybe. But it’s a question I couldn’t avoid.”
We ordered coffee.
After several minutes, Logan admitted he’d known Chelsea’s treatment of me was wrong.
“I thought staying out of it would keep the peace.”
“It kept peace for you,” I answered. “Not for me.”
His eyes reddened.
“I was embarrassed.”
“Of me?”
“No. Of how we treated you.”
For the first time, I believed he understood something beyond the money.
Then he asked how much I actually had saved.
“That’s private, Logan.”
“But Chelsea says you must have a fortune.”
“The amount doesn’t change what happened at dinner.”
He stared at his coffee.
Before leaving, I told him I loved him, but I would never again finance a lifestyle he couldn’t sustain.
That evening, Logan went home and searched through the old filing cabinet I’d left behind.
Inside was the renovation agreement, several bank statements, and a four-year-old document used when his business credit line was renewed.
He unfolded it beneath the kitchen light.
There, beside my name, was the verified value of my investment portfolio.
$803,417.29.